
Turning 65 or New to Medicare in Tampa Bay and Orlando?
Get Free, Unbiased Medicare Enrollment Help From a Local Independent Broker
Medicare Doesn't Have to Be Complicated
Whether you’re approaching your 65th birthday, recently retired after working past 65, or enrolled in Medicare through a disability — navigating your options for the first time can feel overwhelming.
Medicare comes with enrollment windows, plan types, coverage gaps, and costs that vary by carrier, zip code, and health situation. Making the wrong choice at the start can mean paying more than you should, or losing access to the doctors you rely on.
That’s where Timothy Gibson comes in.
Timothy is an independent, licensed Medicare insurance broker serving the Tampa Bay and Orlando area. He is not employed by any single insurance company — he represents 17 carriers and provides a real comparison of all your available options at no cost to you.
His service is free. There is no obligation. And with 16 years of Medicare industry experience, he’s guided many of Florida residents through enrollment just like yours.
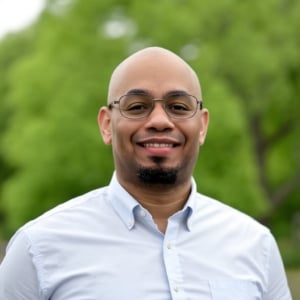
Timothy Gibson
Licensed Independent Medicare Broker | FL License P096286 | NPN 8832650
Serving Hillsborough, Pinellas, Pasco, Polk, Orange, Seminole, Osceola, Hernando, Sarasota, Manatee & Desoto Counties
Who This Page Is For
Turning 65
You’re approaching Medicare eligibility. Your Initial Enrollment Period (IEP) is a 7-month window that begins 3 months before your 65th birthday month and ends 3 months after. Missing it without a qualifying exception can result in permanent late enrollment penalties. Timothy helps you understand exactly when to enroll and which plan type fits your situation.
Working Past 65 or Recently Retired
If you delayed Medicare enrollment because you had employer coverage past age 65, you qualify for a Special Enrollment Period (SEP) when that coverage ends. The rules around coordination with employer insurance are specific — and getting them wrong leads to gaps in coverage or late penalties. Timothy walks you through your transition step by step.
Under 65 With Medicare
If you’re under 65 and enrolled in Medicare through Social Security Disability Insurance (SSDI), you have access to the same Medicare plan options as beneficiaries over 65 — with some important differences in Medigap eligibility depending on your state. Timothy helps you understand your rights and find the best coverage for your situation.
Your Two Main Medicare Decisions at Enrollment
When you first become eligible for Medicare, you make two fundamental choices. Timothy helps you think through both clearly and without pressure.
**Decision 1: Original Medicare or Medicare Advantage?**
Original Medicare (Parts A and B) is administered by the federal government and works with most doctors and hospitals in the country. It comes with deductibles and cost-sharing that many beneficiaries choose to supplement. Medicare Advantage (Part C) is offered by private insurance companies, may include extra benefits like dental and vision, and typically has lower premiums — but with network restrictions and varying out-of-pocket costs.
**Decision 2: If you choose Original Medicare — do you add a Supplement?**
Medicare Supplement plans (Medigap) such as Plan G and Plan N pick up much of the cost-sharing Original Medicare leaves behind. If you choose Medicare Advantage instead, a separate supplement is not used — the Advantage plan itself provides your total coverage.
Neither path is universally better. The right choice depends on your doctors, your prescriptions, your health, and your budget. That’s exactly the conversation Timothy has with every new client.
Key Medicare Enrollment Periods Explained
Initial Enrollment Period (IEP)
The IEP is your first opportunity to enroll in Medicare. It lasts 7 months — starting 3 months before the month you turn 65, the month of your birthday, and the 3 months after. Enrolling before your birthday month means your coverage starts on the first day of your birthday month. Waiting until after can delay your start date by one to three months.
Special Enrollment Period (SEP)
If you delayed Part B because you were covered by employer-sponsored insurance through active employment, you qualify for a Special Enrollment Period when that coverage ends. You have 8 months to enroll in Part B without a late penalty. This is one of the most misunderstood areas in Medicare — and one where Timothy’s guidance prevents costly mistakes.
Annual Enrollment Period (AEP)
Every year from October 15 through December 7, existing Medicare beneficiaries may switch, join, or drop a Medicare Advantage or Part D prescription drug plan. Changes take effect January 1 of the following year. If your current plan is changing its benefits, network, or formulary — AEP is your window to act.
Open Enrollment Period (OEP)
From January 1 through March 31 each year, people already enrolled in a Medicare Advantage plan may switch to a different Advantage plan or return to Original Medicare. This period does not apply to Medigap enrollment, and it cannot be used to enroll for the first time.
What to Expect When You Work With Timothy
Step 1: Free Consultation
Call, text, or book online. No pushiness, no pressure — just a conversation about your situation.
Step 2: Plan Review
Timothy reviews available plans in your county — Medicare Advantage, Medigap, and Part D — and clearly explains your options.
Step 3: Your Decision
You choose the plan that fits your needs, then Tim will assist with the enrollment. There is never a cost to you for his services.
Step 4: Ongoing Support
Timothy remains your broker year over year — available for questions, plan reviews at AEP, and coverage changes as your situation evolves.
Frequently Asked Questions: New to Medicare
When exactly should I sign up for Medicare if I'm turning 65?
The safest time to enroll is during the 3 months before your birthday month. For example, if you turn 65 in July, your enrollment window opens April 1. Enrolling by June 30 ensures your Part B coverage starts July 1, with no gap. If you wait until your birthday month or after, your start date shifts forward by one to three months depending on when you submit. If you have employer coverage and are not yet retiring, speak with Timothy before enrolling in Part B — the rules are different and getting this wrong can affect your benefits.
What is the difference between Medicare Part A and Part B?
Medicare Part A covers inpatient hospital care, skilled nursing facility stays, hospice, and some home health services. Most people receive Part A at no premium cost if they or a spouse paid Medicare taxes for at least 10 years. Medicare Part B covers outpatient services — doctor visits, preventive care, lab work, durable medical equipment, and some home health services. Part B has a monthly premium; in 2026, the standard premium is $202.90 per month, though higher-income beneficiaries pay more through IRMAA surcharges. Together, Parts A and B make up Original Medicare.
Do I have to pay for Medicare if I'm under 65 and on disability?
If you qualify for Medicare through SSDI, you are enrolled in Part A and Part B automatically after a 24-month waiting period from your disability start date. Part A is generally premium-free. Part B carries the same $202.90/month standard premium in 2026 as it does for beneficiaries over 65. You may be eligible for Extra Help or a Medicare Savings Program to reduce your costs depending on your income. Timothy can walk you through what may be available in your specific situation.
What is the penalty for missing my Medicare enrollment window?
If you miss your Initial Enrollment Period for Part B and do not have a qualifying Special Enrollment Period, you may face a late enrollment penalty of 10% of the standard Part B premium for each full 12-month period you were eligible but did not enroll. That penalty is permanent — it stays with your premium for as long as you have Part B. Part D (prescription drug coverage) has a similar late penalty of 1% per month of the national base premium. These penalties are avoidable with proper planning. Contact Timothy before your window closes.
Can I keep my current doctors when I switch to Medicare?
It depends on which type of Medicare coverage you choose. Original Medicare is accepted by the vast majority of doctors, specialists, and hospitals nationwide — if your provider accepts Medicare, they accept it regardless of the insurance company. Medicare Advantage plans have networks that vary by carrier and plan. If keeping a specific doctor is a priority, Timothy verifies network participation before recommending any Advantage plan. This is one of the most important things to check before enrolling.
How does Medicare work if I'm still working and covered by my employer's insurance?
If your employer has 20 or more employees, your employer plan is primary and Medicare is secondary. In this situation, many people delay Part B enrollment to avoid paying the premium for coverage they don’t need yet. When your employer coverage ends — whether because you retire or lose the coverage — you enter an 8-month Special Enrollment Period to enroll in Part B without penalty. The key is having documentation of your employer coverage to prove continuous creditable coverage. Timothy helps you time this transition correctly to avoid gaps or penalties.
Is Medicare Advantage or a Medicare Supplement better for someone new to Medicare?
There is no single correct answer — the right choice depends on your health, your preferred doctors, your prescription drug use, and your budget. Medicare Advantage plans may offer $0 premiums and extra benefits like dental and vision, but typically require in-network care and have copays and coinsurance for services. Medicare Supplement plans (Medigap) have monthly premiums but significantly reduce your out-of-pocket costs and allow you to see any Medicare-accepting provider nationwide. For people who are healthy, budget-conscious, and comfortable with network restrictions, Advantage plans may work well. For people who value predictable costs and maximum provider access, Medigap is often the better long-term fit. Timothy compares both paths for your specific situation — without steering you toward either one.
Does Timothy charge anything for his Medicare help?
No. Timothy’s services are completely free to you. As a licensed independent broker, he is compensated directly by the insurance carriers when a plan is enrolled — at no cost to the client. This compensation structure is standardized and regulated, meaning Timothy earns the same commission regardless of which plan you choose. That means his only incentive is to recommend the plan that genuinely fits your needs.
Plans Timothy May Help You Compare
As an independent broker, Timothy represents 17 insurance organizations. Available plans may include options from the following carriers in your county.
Medicare Advantage Plans
Available Medicare Advantage plans in the Tampa Bay and Orlando area may include options from:
– Freedom/Optimum HealthCare
– Cigna
– AARP / UnitedHealthcare
– Devoted Health
– BayCarePlus
– First Health
– Humana
– Aetna
– And more!
Plans, premiums, networks, and benefits vary by county and change annually. Timothy compares all available options for your specific zip code.
Medicare Supplement (Medigap)
Popular Medigap plans available in Florida may include:
– Plan G — one of the most comprehensive supplement options available to new enrollees
– Plan N — lower premium than Plan G with modest copays
– High-Deductible Plan G (HDG) — lower monthly premium with a higher annual deductible threshold before the plan pays
Timothy compares rates from multiple carriers for the same plan letter — because the benefits are standardized but premiums vary significantly between companies.
Part D Prescription Drug Plans
If you choose Original Medicare with a Medigap plan, you will need a separate Part D prescription drug plan. Timothy reviews your current medications against available Part D formularies in your area to help identify plans that may cover your drugs at the lowest out-of-pocket cost. Enrollment in a creditable Part D plan at the time you become Medicare-eligible avoids a permanent late enrollment penalty.
Ready to Get Your Medicare Questions Answered?
Call or book online for a free, no-obligation Medicare consultation. Timothy serves the Tampa Bay, Polk and Orlando Metro areas — You deserve a better broker.
Timothy Gibson | Licensed Independent Medicare Broker | FL License P096286 | NPN 8832650 | 813-501-5011 | healthplan4u.com
2701 W. Busch Blvd, Suite 279, Tampa FL 33618 | Serving Hillsborough, Pinellas, Pasco, Polk, Orange, Seminole, Osceola, Hernando, Sarasota, Manatee & Desoto Counties